The October CPI report landed on Tuesday with a number that, for once, matters more for what it triggers than for what it measures. Consumer prices rose 0.4% in October and core prices rose 0.3%, both a tenth above forecasts. Within hours, traders went from expecting a possible December rate hike to treating one as settled. For anyone carrying a credit card balance, a home equity line or a mortgage application, that shift is already being priced in.
This piece skips the market play-by-play. Instead, it works through what the data actually say, why this month’s report is missing its usual headline figure, and what a quarter-point or half-point Fed move would cost the typical American borrower in dollars.
The October CPI numbers that moved markets
According to the Bureau of Labor Statistics release, the all-items index climbed a seasonally adjusted 0.4% after a 0.6% jump in September. Shelter rose 0.3% and accounted for more than 30% of the monthly increase. Food rose 0.5%, its largest gain of the year, while energy slowed sharply to 0.7% after a 5.2% surge the month before.
Economists surveyed by Dow Jones had expected 0.3% on the headline and 0.2% on core, CNBC reported. The miss was small. However, it was the third straight month that core inflation came in at 0.3%, and that pattern is what rattled bond traders. Two-year Treasury yields jumped 17 basis points to 4.73%, the biggest one-day move in 19 months, and the 10-year yield touched 5%.
Why there is no annual inflation rate this month
Readers looking for the familiar line about inflation over the past year will not find it in the official release. Because of the 2025 government shutdown, BLS did not collect survey data for October 2025. As a result, it cannot publish 12-month changes for most October 2026 indexes, so the October CPI arrives without its usual annual figure.
That gap creates a real problem for anyone who relies on a year-over-year figure, from union contracts to rent escalation clauses. Private analysts have filled it with estimates. For example, Haver Analytics estimated the missing October 2025 value and calculated annual headline inflation of 4.1%, the highest since May, with core at 2.8%. Those are estimates, not official statistics, so treat them as a guide rather than a contract number.
Three months of 0.3% core adds up fast
Monthly figures in the October CPI can look harmless. A 0.3% rise sounds like a rounding error. Yet compounding changes the picture. If core prices kept rising 0.3% a month for a year, core inflation would run at roughly 3.7%, almost double the Fed’s 2% goal.
The headline measure looks worse. Over August, September and October, the all-items index rose 0.4%, 0.6% and 0.4%. That is about 1.4% in three months. Annualized, it works out to roughly 5.7%. Gasoline drove much of September’s jump, so that number will probably cool. Even so, the core trend is the one policymakers watch, and it has not budged.
Waller set a bar, and the October CPI cleared it
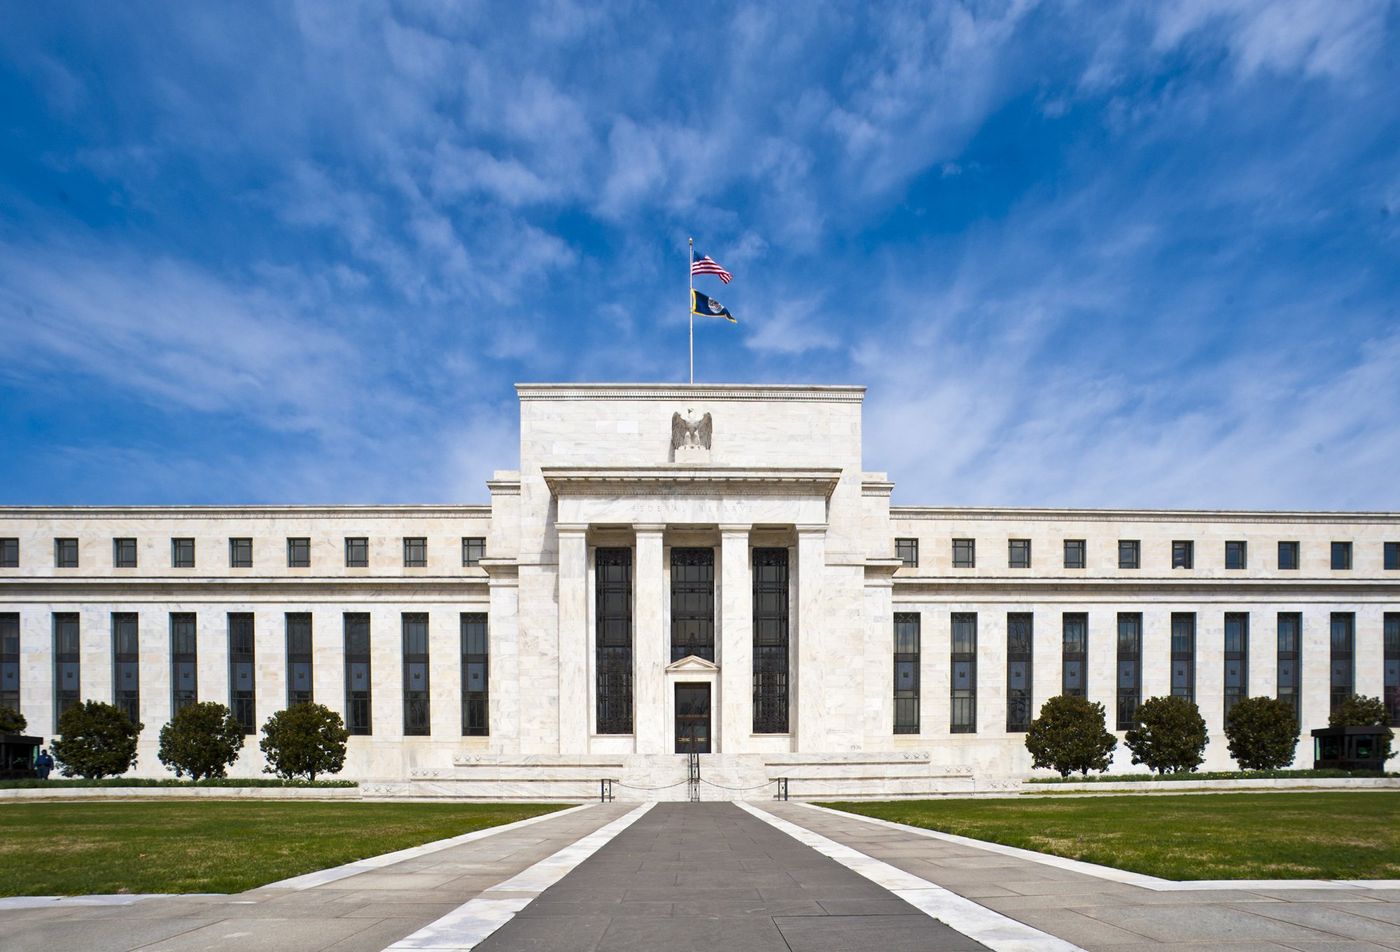
The timing made Tuesday unusual. Hours before the data came out, Fed Governor Christopher Waller told an audience in London that he was already leaning toward a 25-basis-point increase at the December 8-9 meeting. He then drew a line in advance. In his published speech, he said that if core CPI came in “around 0.3 percent or even higher,” a 50-basis-point hike “should be considered,” and that hiking only 25 basis points “would put our credibility at risk.”
Core came in at exactly 0.3%. After the release, futures markets fully priced a quarter-point hike in December, and CNBC cited CME FedWatch odds of about 13.6% for a half-point move, up from close to zero. The Fed held its target range at 3.75% to 4% on October 28, according to its FOMC statement, although two officials, Lisa Cook and Beth Hammack, voted for an immediate increase. In short, the committee was already split before this report.
What a quarter-point hike means for a credit card balance
Most US credit card rates are tied to the prime rate, which banks typically set three percentage points above the top of the Fed’s range. That would put prime at about 7% today. A December hike would push it to 7.25%, or 7.5% after a half-point move, and card APRs would follow within a billing cycle or two.
The New York Fed’s quarterly household debt report, released the same day as the inflation data, put credit card balances at a record $1.285 trillion. Using that figure, a quarter-point increase adds about $3.2 billion a year in interest across all card balances, assuming the full move passes through. A half-point hike doubles that to about $6.4 billion.
Per person, the number is smaller than the headlines suggest. TransUnion puts the average balance at $6,678. On that balance, a quarter-point rise costs about $17 a year, and a half-point rise about $33. Consequently, the December decision on its own will not break most budgets. The bigger risk is the cumulative path: futures are pricing roughly three quarter-point hikes by June, and each one stacks on the last.
HELOCs, mortgages and the 5% Treasury yield
Home equity lines of credit deserve more attention than they usually get. Balances rose $23 billion last quarter to $481 billion, the largest increase since 2005, according to the New York Fed. Because most HELOCs float with prime, a quarter-point hike adds roughly $1.2 billion a year to those payments. The October CPI therefore matters directly to these households. Many took these lines as a cheaper alternative to refinancing, and that calculation is now shifting.
Fixed-rate mortgages work differently. They track longer-term Treasury yields rather than the Fed’s overnight rate. Meanwhile, the 10-year yield reaching 5% is the more direct threat to anyone shopping for a home loan this month. Buyers who are close to locking a rate may want to weigh that move now rather than wait for the December meeting, since bond markets have already reacted.
Where the October CPI hit household budgets
The line items explain why the report felt different from September’s. Beef rose 0.9% and snacks rose 1.0%. Full-service restaurant meals climbed 0.7%. Motor vehicle insurance rose 0.7%, and hospital services rose 0.8%. In contrast, used cars and trucks fell 1.2%, one of the few categories offering relief.
Gasoline is a useful reminder about seasonal adjustment. The adjusted gasoline index rose 1.0%, yet before adjustment, pump prices actually fell 0.7% in October. In other words, drivers paid less, but less than the usual seasonal drop. Over 12 months, the unadjusted gasoline index is still up 37.4%, one of the few annual figures BLS could publish.
The calendar quirk that leaves the Fed without new price data
One detail has received little attention. The November CPI is scheduled for December 10, a day after the Fed’s December 8-9 meeting ends. That makes the October CPI the last consumer price report policymakers will see before they vote. Haver Analytics made the same point, noting that only one more jobs report arrives before the meeting.
For borrowers, that means the main inflation evidence is now in. Unless the November jobs data surprise sharply, the debate inside the Fed is less about whether to raise rates and more about how much. We have tracked how this year’s market stories connect, from the Anthropic IPO filing to the questions facing Nvidia’s board and the fight over Texas data centers. Higher borrowing costs now run through all of them.
For households, the practical takeaway is simple. Paying down variable-rate debt, especially card balances and HELOCs, is worth more this month than it was in September. The October CPI did not change the direction of travel. However, it removed most of the doubt about the next step.