China capital injection plans will add about 360 billion yuan, or $54 billion, to major state banks and insurers. Beijing wants to reinforce institutions facing weaker margins while supporting the wider economy.
The China capital injection package, announced on Sunday, 6 September 2026, combines direct state support with private share placements. China’s finance ministry leads the effort. State-owned tobacco companies will also participate in bank placements.
China capital injection covers banks and insurers
Reuters reported that three state lenders will receive a combined 290 billion yuan. Agricultural Bank of China plans to raise as much as 160 billion yuan, while Industrial and Commercial Bank of China is targeting up to 100 billion yuan through private placements to the finance ministry, China National Tobacco Corporation and related companies.
The Export-Import Bank of China is due to receive another 30 billion yuan from the finance ministry. The policy lender said the funding would strengthen its capital base and its ability to support economic activity and manage risk.
The China capital injection will direct the remaining 70 billion yuan to state-owned insurers. China Life Insurance Group will receive 35 billion yuan, while China Taiping Insurance Group will receive 7 billion yuan. People’s Insurance Company of China plans to raise up to 15 billion yuan through a private placement to the finance ministry.
China Export and Credit Insurance Corporation is due to receive 10 billion yuan, while China Reinsurance Group plans to raise 3 billion yuan. Together, the announced banking and insurance transactions add up to the roughly 360 billion yuan total.
Why Beijing is strengthening financial capital
Capital is the financial cushion that allows a bank or insurer to absorb losses while continuing to meet obligations. Adding core capital can therefore support lending, protect policyholders and reduce the risk that stress at one institution spreads through the system.
For Agricultural Bank of China and ICBC, the China capital injection will replenish core Tier 1 capital. This is the highest-quality form of bank capital and a central measure of resilience under banking rules.
Beijing has also relied on large state banks to maintain credit as the economy confronts weak loan demand. That policy role can put pressure on profitability because banks may be asked to lend more even when interest margins are narrow.
Reuters said persistently low interest rates have also hurt insurers’ investment returns and profitability. Some small and medium-sized insurers have reported weaker solvency ratios, increasing the importance of stronger balance sheets at large state groups that may be called on to help stabilize the sector.
A broader recapitalization strategy
China’s government outlined the bank component during its annual parliamentary meeting in March. The plan extends a recapitalization programme that strengthened other large state lenders in 2025.
The Financial Times independently reported the 360 billion yuan package and said the finance ministry would provide 300 billion yuan through special bonds, with state tobacco companies supplying another 60 billion yuan.
The South China Morning Post also confirmed the scale and named Agricultural Bank of China, ICBC and the Export-Import Bank among the recipients. It described the measures as part of a more proactive fiscal approach to growth pressures.
These are not ordinary government spending payments. The transactions add capital to financial companies in exchange for shares or stronger state ownership positions. The money therefore remains tied to institutions that lend, insure and invest across the economy.
Why the China capital injection matters
China operates one of the world’s largest banking systems, so changes in its state lenders can affect corporate borrowing, infrastructure financing and trade credit well beyond the country’s borders.
Stronger capital ratios may give the banks more room to lend without weakening regulatory safeguards. For insurers, additional capital can improve solvency and provide a larger buffer against market losses or claims.
The China capital injection also shows how Beijing uses state-controlled institutions as an economic-policy channel. The government can strengthen banks and insurers, then encourage them to finance priority sectors. This approach works alongside interest-rate cuts and direct public spending.
That approach has limits. New capital can improve resilience, but it cannot create profitable borrowers or eliminate credit risk. If companies and households remain cautious, banks may still struggle to expand good-quality lending.
What to watch next
The next stage for the China capital injection is completing the share placements and direct funding. Some transactions still need regulatory or shareholder approval. Investors will also watch core Tier 1 ratios, insurer solvency measures and lending growth.
Another question is whether the package leads to more credit for productive private investment or mainly protects institutions from weaker earnings. The answer will help determine whether the recapitalization supports broader growth or functions primarily as a financial-stability measure.
For now, the China capital injection stands out for its breadth. Beijing is strengthening commercial banks, a policy lender and major insurance groups in one coordinated round rather than through isolated rescues.
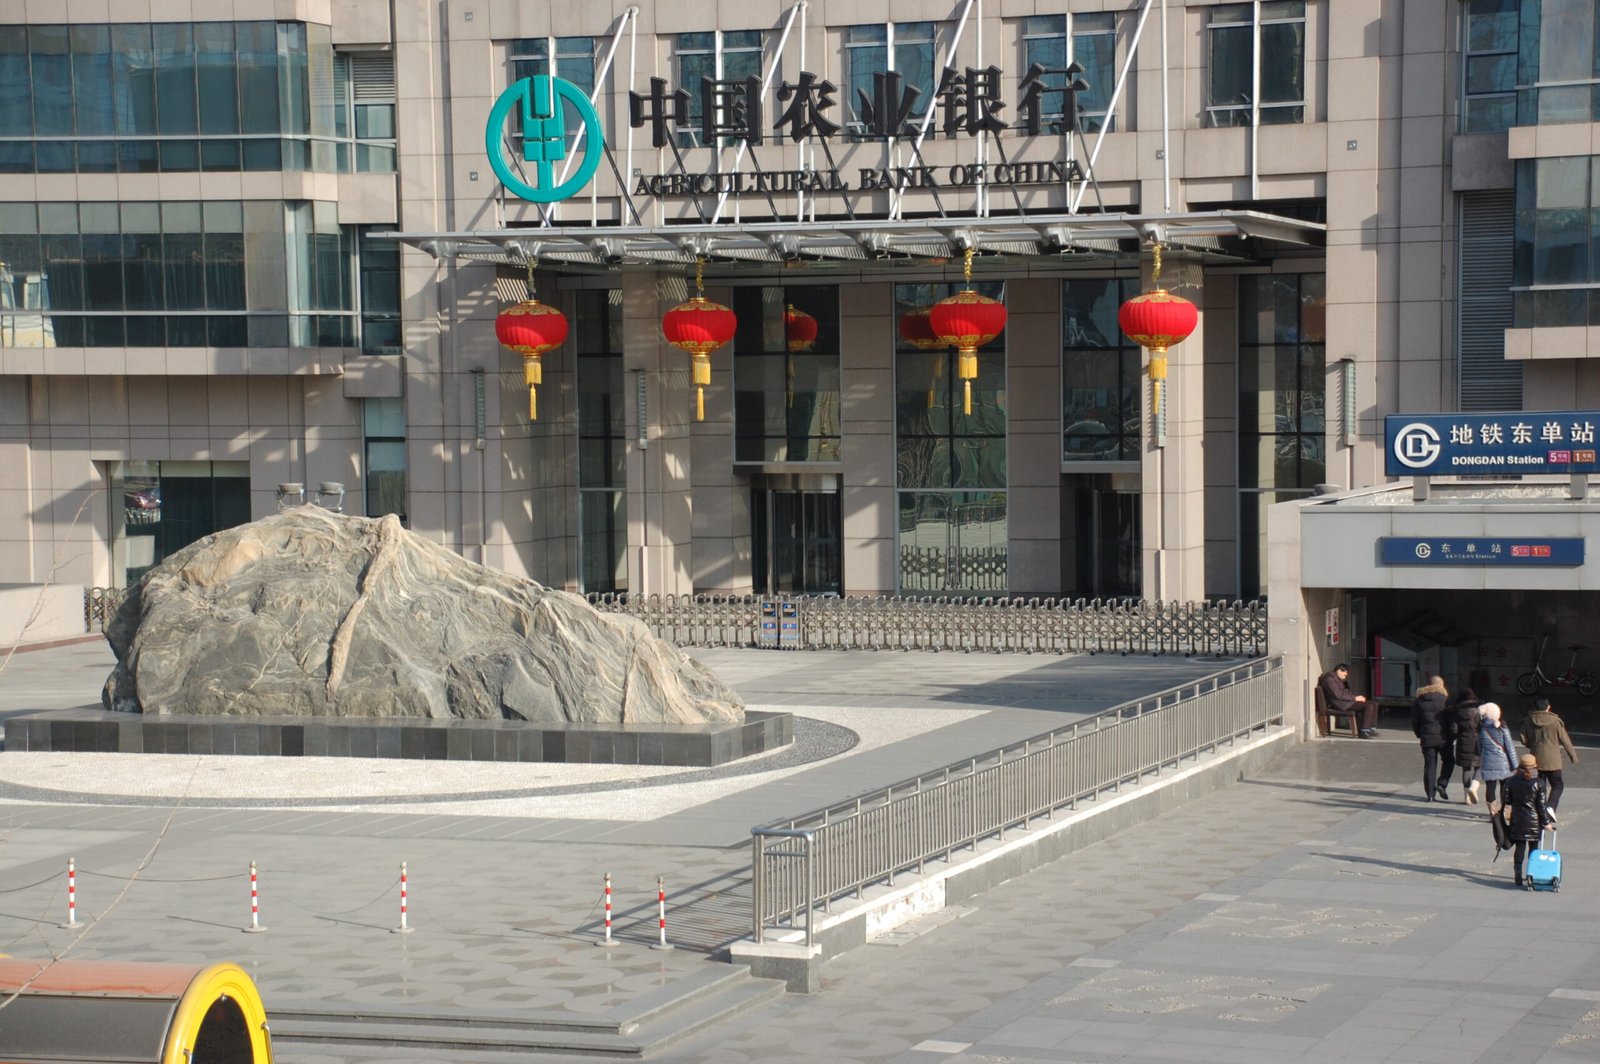
Featured image: File photograph of an Agricultural Bank of China branch in Beijing, taken 14 January 2012. Photo: Voice of America, via Wikimedia Commons. Public domain in the United States; Public Domain Mark 1.0.
Read more in The Daily Vantage’s Business section.